In short
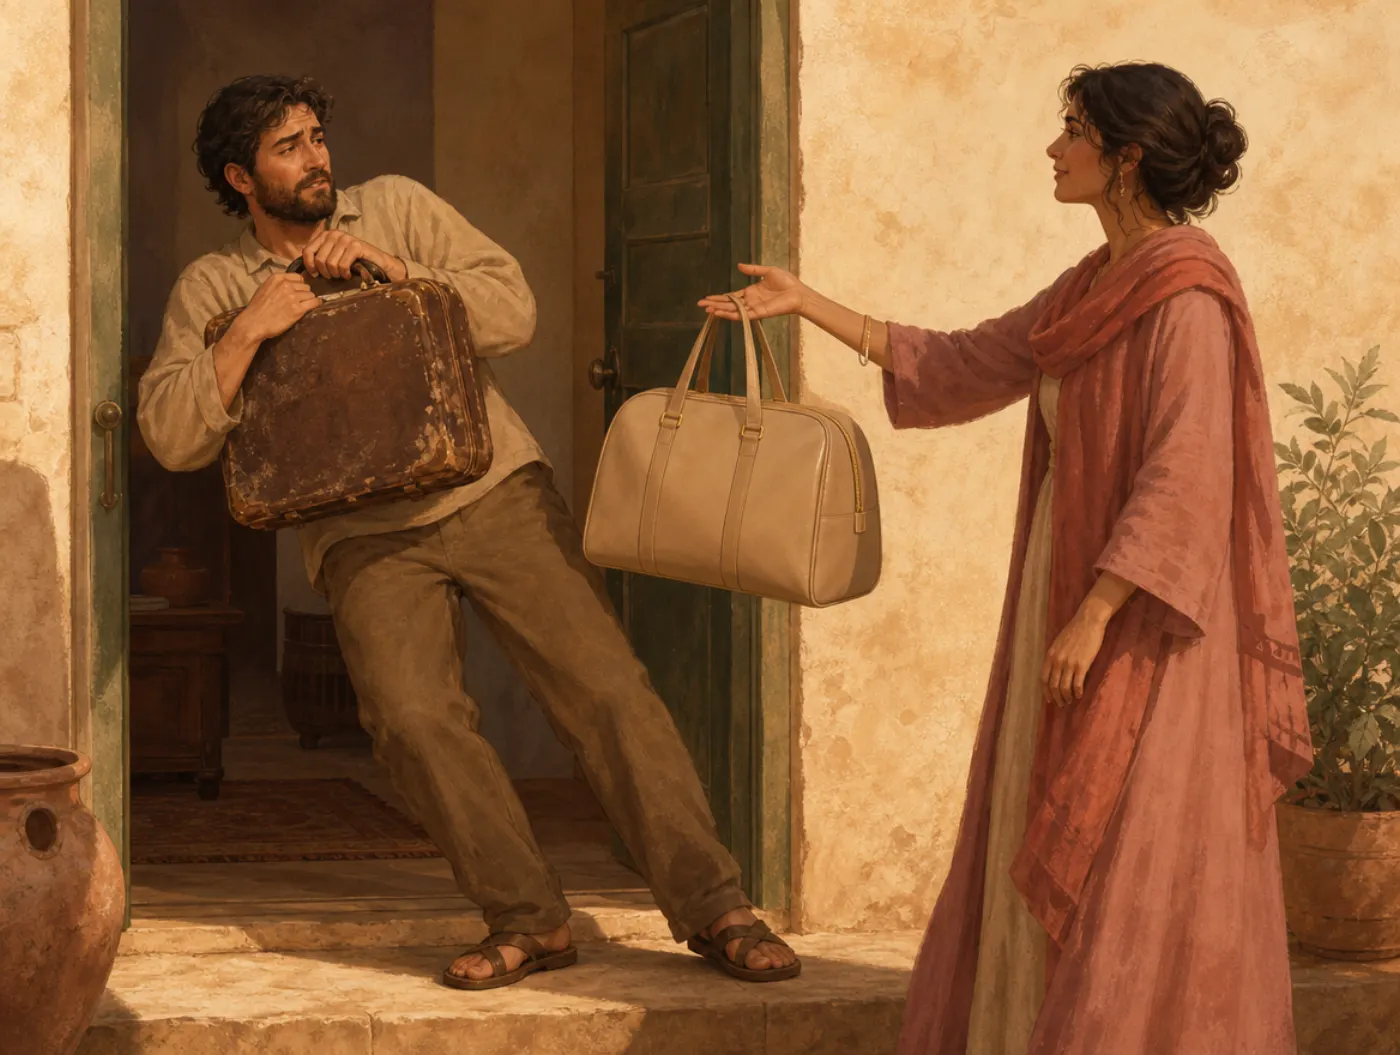
Loss aversion is the tendency for a loss to weigh more heavily in a decision than a gain of the same size, so that people turn down even-money gambles and work harder to avoid giving something up than to get it. It shows up in investors holding losing positions, shoppers who keep a subscription they would never buy again, negotiators who treat a concession as a wound, and anyone who has stayed in a situation because leaving felt like losing.
How loss aversion works
Decisions are made from a reference point rather than from a total. Prospect theory describes people as evaluating outcomes as gains and losses relative to where they currently stand, and the curve that turns outcomes into feelings is steeper on the loss side than on the gain side. Twenty dollars gained and twenty dollars lost are the same size on a bank statement and different sizes in a decision.
That asymmetry explains a pattern that pure arithmetic cannot. A fifty-fifty bet to win 110 dollars or lose 100 has a positive expected value and is still refused by people who understand the odds, because the prospective loss counts for more than the slightly larger gain. When Tversky and Kahneman fitted their 1992 model to the choices of 25 graduate students, the median coefficient on losses came out at 2.25, which is where the rule of thumb that losses weigh about twice as much comes from.
Because the reference point does the work, the same decision can be made to look like a gain or a loss. A 5 percent price increase presented as the loss of a discount is resisted more than the same number presented as a smaller gain. An employer offering a bonus for hitting a target gets a weaker response than one that hands it over up front and takes it back on a miss.
Loss aversion is also the simplest explanation for inertia. If giving something up hurts more than getting it would please, the current arrangement wins by default: the subscription stays, the portfolio is not rebalanced, the job is not left. The reluctance to sell a losing investment and the premium owners place on what they own follow from the same steepness.
The size and the generality of the effect are argued over, and what the asymmetry measures with them. Gal and Rucker reviewed the evidence in 2018 and concluded that losses are not reliably more impactful than gains once the studies that use status quo defaults and other confounds are set aside, and they describe the universal version of the claim as unsupported. They also question the gambles themselves: refusing a bet with a positive expected value is also consistent with ordinary risk aversion or a dislike of gambling, so a refused bet is not by itself proof of the asymmetry. Other work keeps the effect but draws boundaries around it: Novemsky and Kahneman proposed in 2005 that money given up as intended in an ordinary purchase is generally not subject to loss aversion, and set out other conditions under which the asymmetry weakens.
The original study
Daniel Kahneman and Amos Tversky set out prospect theory in Econometrica in 1979, in a paper that used hypothetical choice problems to document where expected utility theory fails. Respondents chose between pairs of gambles, and three patterns emerged: outcomes were valued as changes from a reference point rather than as final states, the pattern of choices reversed when gains were turned into losses, and small probabilities were overweighted. The paper's value function is concave for gains, convex for losses and steeper on the loss side, and the sentence that the steeper side produced, losses loom larger than gains, is the one that became the name of the effect.
The 1979 paper did not put a number on the steepness. That came in 1992, when Tversky and Kahneman published "Advances in prospect theory" in the Journal of Risk and Uncertainty. Twenty-five graduate students from Berkeley and Stanford, none with training in decision theory, worked through a long series of choices between gambles and sure amounts, and the authors fitted the theory's value and weighting functions to each person's answers. The median estimates were 0.88 for the curvature of the value function and 2.25 for the loss aversion coefficient. That 2.25 is an estimate from a small sample of students answering about hypothetical money, not a constant of human nature; later estimates vary.
Field studies then looked for the same asymmetry in real decisions, from investors who sell winners and hold losers to reluctance to trade goods people already own, and a long argument began about what the coefficient measures, which Gal and Rucker's 2018 review brought to a head by asking how much of the evidence rests on tasks where the alternative to a loss is doing nothing.
Everyday examples
The pattern turns up wherever a choice can be framed around something a person already has. The rows below are illustrations, not findings from the studies cited on this page.
| Situation | What the bias does | What helps |
|---|---|---|
| A free trial that becomes a paid subscription | Canceling now feels like giving up the service, so the charge continues | Ask what you would pay for it today if you did not have it, then decide |
| A share that has fallen 30 percent | Selling makes the loss final, so the position is held and the money stays tied up | Decide from the position's prospects, not its purchase price, and write the rule before you need it |
| An extended warranty on a cheap appliance | The small chance of a loss is paid to remove, at a price well above the expected cost | Compare the premium with the replacement cost multiplied by the chance of needing it |
| A pay offer with a lower bonus and higher base | The reduced bonus reads as a cut, even when the total is higher | Compare total packages as final amounts, written side by side |
| A project that is clearly not working | Stopping registers as losing the work so far, so it continues | Ask what you would start today with the same budget and the same information |
How to counter it
The counters all work by moving the reference point out of the way.
- Restate the options as final states. "End the year with 48,000 dollars or with 50,000 dollars" is the same choice as "lose 2,000" with the sting taken out of it.
- Decide once for many cases. A rule applied to a long run of similar bets collects the average, which for many favorable gambles is reliably positive even though each one feels risky.
- Use the ownership test. If you did not already hold this stock, this subscription or this plan, would you buy it now at today's price? If not, holding it is a decision you never actually made.
- Write the exit condition at the start. Rebalancing dates, stop rules and review dates are decisions taken before a loss exists to be avoided.
- Name the opportunity cost. Money left in a losing position is also money not working somewhere else, which is a loss that no reference point makes vivid.
- Expect the asymmetry in other people. Concessions, price rises and benefit changes land harder than the equivalent gains, so they need more notice, more explanation and sometimes a different design.
What it is not
Loss aversion sits in a family of effects about holding, keeping and giving up, and the differences matter.
- It is not the endowment effect, which is the specific finding that people demand more to give up an object than they would pay to acquire it. Loss aversion is the general asymmetry that is usually offered as its explanation, and the two are tested in different ways.
- It is not the sunk cost fallacy, which is about past spending influencing a present decision. Loss aversion is about a prospective loss, and it can push someone to quit early as easily as to carry on.
- It is not status quo bias, the preference for leaving things as they are. Status quo bias describes the behavior; loss aversion is one of its proposed causes, and separating the two is the heart of the current argument about how large the effect really is.
- It is not risk aversion, the general reluctance to take a gamble over a sure thing. A refused even-money bet is consistent with either, so the demo above describes your answers without naming a cause.
Go deeper: the free Loss Aversion mini course
Twelve to fifteen minutes, in your browser, with the research behind the bias and the counter-measures that have evidence.
Tests and tools that use this
Related biases
Loss Aversion FAQ
What is loss aversion in simple terms?
It is the tendency for a loss to count for more than a gain of the same size. Losing 100 dollars feels worse than winning 100 dollars feels good, so people turn down even-money bets and resist giving up things they already have. Tversky and Kahneman's 1992 estimate put the ratio at about 2.25 to 1 for the students they tested, which is where the rule of thumb that losses weigh twice as much comes from.
Is loss aversion irrational?
Not by itself. Declining a single coin flip for money you cannot afford to lose is sensible, and prospect theory describes rather than condemns the pattern. The costly part is applying the same caution to a long run of favorable decisions, where the average outcome is what matters, and letting the reference point decide instead of the amounts. The demo on this page asks about one flip at a time for that reason.
How did the demo on this page measure anything?
You set the smallest win you would accept on three hypothetical flips with different stakes. Each slider started at the stake itself, so an untouched slider means accepting even money, and asking for more than the stake on at least two of the three is what the result records. Each slider stops at twice the stake, so a larger demand is recorded as exactly twice. Wanting a premium is consistent with loss aversion and with ordinary caution about gambling, so the result describes your answers rather than diagnosing their cause.
Where does the 2 to 1 ratio come from?
From Tversky and Kahneman's 1992 paper, which fitted the cumulative version of prospect theory to the choices of 25 graduate students and reported a median loss aversion coefficient of 2.25. It is a median estimate from one small sample answering about hypothetical money. Later studies using other methods report a range of values, and Gal and Rucker's review collects cases in which no asymmetry appears, so 2 to 1 is a rough anchor rather than a constant.
Has loss aversion been challenged?
Yes. Gal and Rucker argued in 2018 that the evidence does not support losses being generally more impactful than gains, because many of the classic demonstrations compare acting with doing nothing, and inertia can produce the same results. The current position is narrower than the popular version: the asymmetry is a consistent finding in the risky-choice tasks it was measured in, whether it reflects loss aversion or a general reluctance to gamble is argued, and how far it generalizes depends on the amounts, the goods and the setting.
How is loss aversion used in marketing and product design?
Mainly by giving people something to lose. Free trials, loyalty points, streaks, status tiers and limited-time offers all create a holding that ending the relationship would forfeit. None of this requires a hidden mechanism: the practical defense is to ask what you would pay for the thing today if you did not already have it, and to make cancellation decisions on a calendar rather than in the moment.
References
- Kahneman, D., & Tversky, A. (1979). Prospect theory: An analysis of decision under risk. Econometrica, 47(2), 263-291. doi.org
- Tversky, A., & Kahneman, D. (1992). Advances in prospect theory: Cumulative representation of uncertainty. Journal of Risk and Uncertainty, 5(4), 297-323. doi.org
- Gal, D., & Rucker, D. D. (2018). The loss of loss aversion: Will it loom larger than its gain? Journal of Consumer Psychology, 28(3), 497-516. doi.org
- Novemsky, N., & Kahneman, D. (2005). The boundaries of loss aversion. Journal of Marketing Research, 42(2), 119-128. doi.org
- Barberis, N. C. (2013). Thirty years of prospect theory in economics: A review and assessment. Journal of Economic Perspectives, 27(1), 173-196. doi.org
Cite this source
Psychology.com. (2026, October 21). Loss Aversion. Psychology.com. https://psychology.com/biases/loss-aversion