In short
Ambiguity bias is the preference for an option whose odds are known over one whose odds are unknown, even when nothing shows the unknown option to be worse. It is why a familiar employer beats an unfamiliar one on the same salary, why a fund at home beats a fund abroad, and why a treatment with published rates is chosen over one whose rates have never been measured.
How ambiguity bias works
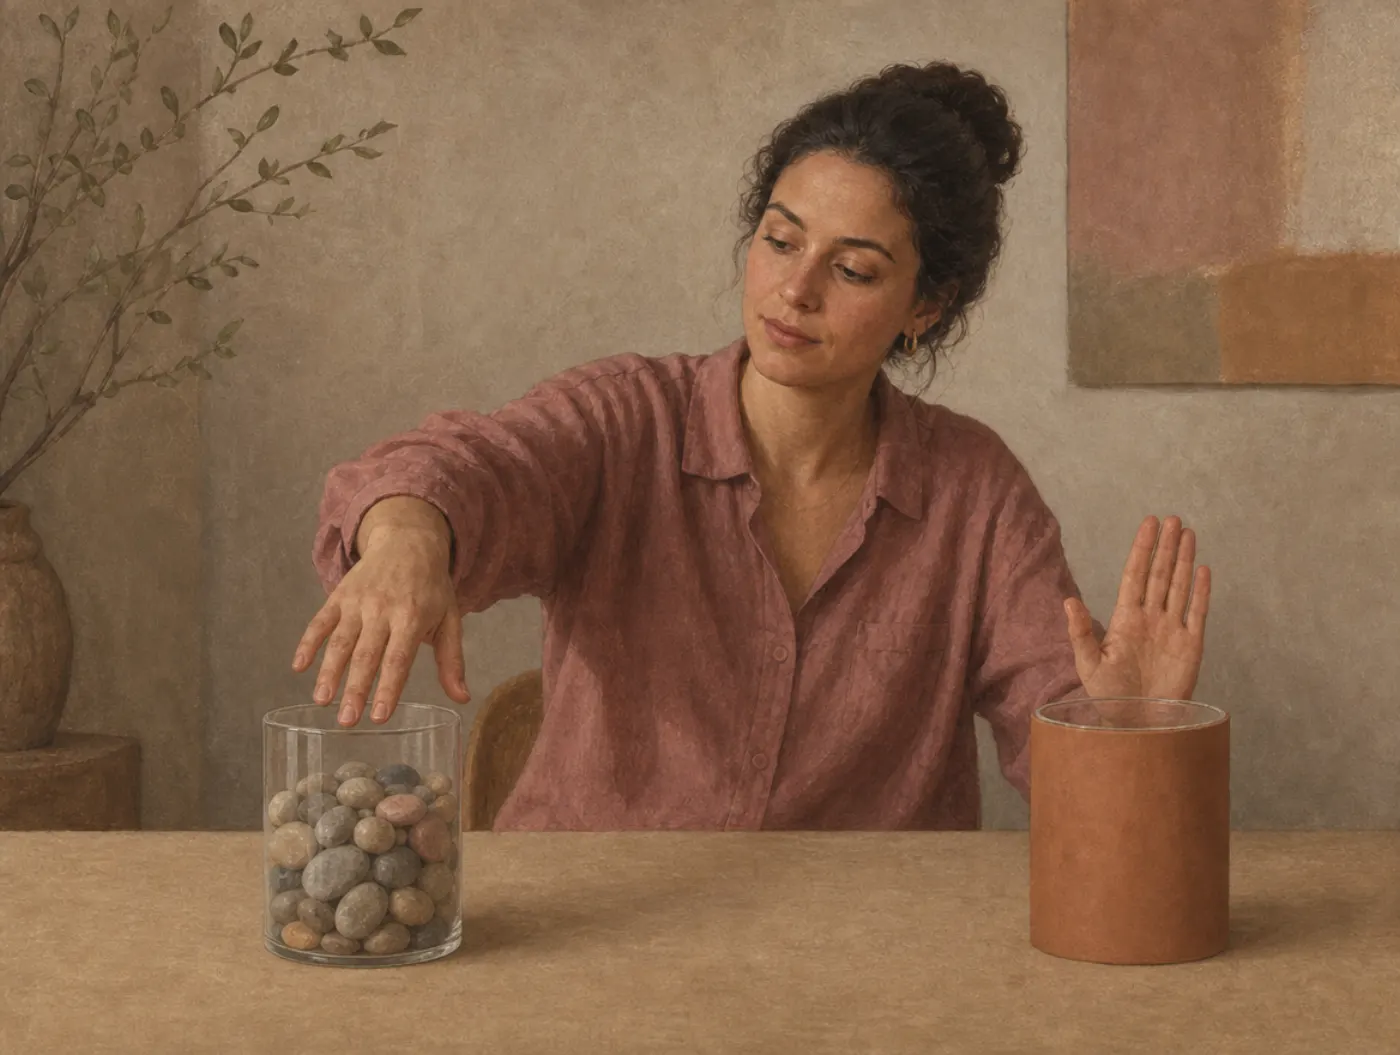
The two urns separate two kinds of not knowing. With the known urn you cannot tell which ball will come out, but you can state the chance exactly: one half. With the unknown urn you cannot state the chance at all, because the proportion was never disclosed. Economists since Frank Knight have called the first risk and the second uncertainty, and ambiguity bias is the extra discount people apply to the second.
What makes the pattern awkward is that it cannot be explained by a belief about the unknown urn. If you prefer the known urn when red wins, you are behaving as though the unknown urn holds fewer than 50 red balls. That same belief means it holds more than 50 black ones, so when black wins, the unknown urn should look better. Most people prefer the known urn in both cases, and no set of probabilities for the unknown urn makes both choices right at once. That is the contradiction Ellsberg used against the axioms of subjective expected utility.
Read the diagram as text
Matched urn outlines differ in visibility: one reveals mixed open and filled balls, while an opaque face hides the other mixture. A chooser’s accent route bends toward the visible urn and leaves the unknown option on a dashed route. The illustrative ball icons do not reconstruct the urn totals or estimate choice shares.
Which urn do you bet on?
No set of odds makes both choices right at once
Same two urns: 50 red and 50 black in one, an unknown mix in the other
Red wins: Known urn chosen, as if the unknown urn held fewer than 50 red balls
Black wins: Known urn chosen, as if the unknown urn held fewer than 50 black balls
Several accounts have been offered for why the unknown urn feels worse. One is simple missing information: an option described by a gap invites the suspicion that somebody chose the gap, and in daily life unknown odds often are set by a party with an interest. A second is the feeling of being unable to defend the choice afterward, since a loss on the known urn was bad luck while a loss on the unknown one was carelessness. A third, from Chip Heath and Amos Tversky, is competence: people prefer to bet in areas where they feel knowledgeable, sometimes accepting worse published odds to do it.
The condition for the effect matters as much as the effect. Craig Fox and Amos Tversky showed that ambiguity aversion is pronounced when a person evaluates the clear and the vague prospect together and largely disappears when separate groups evaluate one of them in isolation, which they called comparative ignorance. The vague urn is not unattractive in itself; it becomes unattractive next to a transparent one. The demo above puts the two side by side, which is the condition under which the effect appears.
The original study
Daniel Ellsberg published "Risk, Ambiguity, and the Savage Axioms" in the Quarterly Journal of Economics in 1961, as an argument rather than an experiment. Leonard Savage's axioms imply that a person behaves as if they had a single set of probabilities for every uncertain event, and Ellsberg's aim was to show that reasonable people knowingly break that rule when the probabilities are not given to them.
He built two problems. The two-urn problem is the one in the demo: 100 balls in each urn, a known 50-50 split in one and an undisclosed mix in the other, with bets offered on either color. The three-color problem puts 30 red balls and 60 balls that are black or yellow in unknown proportion into a single urn, and offers bets that pin the inconsistency down even more tightly. Ellsberg put these to colleagues and seminar audiences, among them Savage himself, and reported the pattern he found: a steady preference for betting on the known proportions, whichever color was named, held by people who understood exactly what the preference implied and kept it anyway. The responses were collected informally and the paper gives no percentages, which is why no share of participants is quoted on this page.
The paper drew an immediate reply from Howard Raiffa in the same issue, and the experimental literature followed. The result that most changed how the effect is understood is Fox and Tversky's in 1995. Across several studies they found that people priced a vague bet well below a clear one when both were in front of them, and priced the two about the same when separate groups saw only one. Heath and Tversky had reported in 1991 that the preference tracks felt competence: people will bet on their own uncertain judgment in a familiar domain over a matched chance device.
The direction of the effect is well replicated in laboratory urn tasks with the two bets presented together. Its size varies a great deal with how the choice is framed and who is choosing, and a sizable minority of people in most studies are not ambiguity averse at all.
Everyday examples
The rows below are places where a known number competes with a missing one, not findings from the studies cited here.
| Situation | What the bias does | What helps |
|---|---|---|
| A job offer from a familiar employer against one from a company nobody can tell you about | The unknown employer is discounted for being unknown rather than for anything found out about it | Spend an hour closing the gap: former employees, filings, a question list for the interview |
| A treatment with published side effect rates against a newer one with none published | The measured risk is preferred even when the unmeasured one may well be smaller | Ask what is known, what is merely unpublished, and what the plausible range is |
| An investor holding mostly domestic stocks | Foreign markets feel unknowable, so a familiar market gets more weight than its returns justify | Compare the actual published numbers side by side before deciding on familiarity |
| Two contractors, one with fifty reviews and one with none | The one with no reviews is treated as bad rather than unrated | Ask the unrated one for references and recent work; absence of data is not data |
| An insurance policy with a clear exclusion list against one that is vague | The vague policy is dropped even when it is cheaper and broader | Ask the insurer to put the ambiguous cases in writing, then compare like with like |
How to counter it
Ambiguity is sometimes a warning and sometimes just a gap in your knowledge. The counter is to tell the two apart instead of discounting both.
- Ask who chose the gap. If the party with the information is the one offering the deal, the missing number is probably not in your favor and the discount is earned. If nobody chose it, the discount is a habit.
- Run the consistency test. State the bet both ways, as the demo does. If you prefer the known option in both directions, at least one of those preferences is not about the odds.
- Write down the range you are actually facing. Unknown rarely means anything is possible: it usually means somewhere between two numbers you could name if asked.
- Buy information before buying certainty. An hour of research often costs less than the premium you are about to pay for the transparent option.
- Evaluate options separately when you can. Ambiguity aversion is strongest in side-by-side comparison, so judge the unfamiliar option on its own terms first.
- Watch the familiarity trap. Feeling competent in a domain is not the same as having better odds in it.
What it is not
Three nearby entries are about missing or unwelcome information, and they differ in what the chooser is reacting to.
- It is not zero-risk bias, the preference for removing one risk completely over a larger cut in total risk. There the probabilities are all known and the pull is toward the last step to zero; here the pull is away from not knowing the probability at all.
- It is not status quo bias, the preference for leaving things as they are. The two often point the same way, since the current option is usually the better understood one, but ambiguity bias also shows up between two options that are both new.
- It is not information bias, the appetite for information that cannot change the decision. Both involve the value put on knowing, but information bias is about collecting numbers you will not use, and ambiguity bias is about avoiding choices where the number is missing.
Tests and tools that use this
Related biases
Ambiguity Bias FAQ
What is ambiguity bias?
It is the preference for an option with known odds over one with unknown odds, even when nothing indicates the unknown option is worse. It is also called ambiguity aversion. The standard demonstration offers a bet on a ball drawn from an urn with a known 50-50 mix or from an urn whose mix was never disclosed, and most people take the known urn whichever color they are playing for.
What is the Ellsberg paradox?
It is the name for the inconsistency in those choices. Preferring the known urn when red wins implies a belief that the unknown urn holds fewer than 50 red balls, which implies it holds more than 50 black ones, so the same person should prefer the unknown urn when black wins. Most people prefer the known urn both ways, and no single set of probabilities makes both choices coherent.
Who was Daniel Ellsberg?
He was a decision theorist at the RAND Corporation when he published the 1961 paper, having worked on the problem in his doctoral research. He is better known outside economics for releasing the Pentagon Papers in 1971. The urn problems in the paper were put to colleagues and seminar audiences rather than run as a formal experiment, and the paper reports the pattern of answers without percentages.
Is avoiding ambiguity irrational?
Not in general. When the missing information is missing because someone chose not to give it, caution is sensible, and unknown odds in real markets are often set by the better informed party. The result the laboratory shows is narrower: in a setting where nobody has an advantage, people pay to avoid the unknown mix, and they do it in both directions at once, which cannot be justified by any belief about the urn.
How did the demo on this page work?
When the page loaded it assigned you one of two versions, red wins or black wins, using a value kept only in your browser's session storage, so a reload shows the same version. Both versions offer the same two urns. The result screen shows the other version in full, and once each has 50 or more responses it shows the live split for the two side by side.
How do I make a decision when the odds are unknown?
Start by asking why they are unknown and who benefits from that. Then write down the range you are really facing, since unknown usually means between two numbers you could name. Spend an hour closing the gap before paying a premium for the transparent option, and test your preference by stating the choice in both directions to see whether it survives.
References
- Ellsberg, D. (1961). Risk, ambiguity, and the Savage axioms. Quarterly Journal of Economics, 75(4), 643-669. doi.org
- Fox, C. R., & Tversky, A. (1995). Ambiguity aversion and comparative ignorance. Quarterly Journal of Economics, 110(3), 585-603. doi.org
- Heath, C., & Tversky, A. (1991). Preference and belief: Ambiguity and competence in choice under uncertainty. Journal of Risk and Uncertainty, 4(1), 5-28. doi.org
- Raiffa, H. (1961). Risk, ambiguity, and the Savage axioms: Comment. Quarterly Journal of Economics, 75(4). doi.org
Cite this source
Psychology.com. (2026, October 23). Ambiguity Bias. Psychology.com. https://psychology.com/biases/ambiguity-bias